The essentials
- Yes, a house share can be financed from abroad: our members obtained loans of up to 25 years from the United Kingdom, Canada, Dubai, Switzerland or Luxembourg.
- The bank counts part of the future rent: often around 70%, which helps stay under the 35% debt-to-income ratio.
- Works and furniture can be included in the loan, with a deferral during the works: 6 to 24 months for our members, 2 years at most.
- Our members’ house shares show gross yields from 8.5% to 12.6%, with rents from €1,240 to €2,540 per month.
- The application is prepared before looking for the property: estimated rent per bedroom, bedroom layout, works quotes and the bank’s agreement in principle.
Can you finance a house share when you live abroad?
Yes. To the bank, a house share is a rental investment like any other: it looks at your income, your outgoings, the cost of the project and the expected rent. The difficulty does not come from the house share, but from the fact that you live abroad: income in a foreign currency, often no French tax assessment, an application read by a branch that sees few non-residents.
A house share even has an advantage: several rents for a single loan. When a bedroom becomes vacant, the others keep paying, and the yield is often higher than with a standard let. It is an argument to put forward to the banker.
What the bank looks at in a house share
- Future rent. Most banks count part of the expected rent, often around 70%, based on an agency or property manager estimate. A realistic rent per bedroom for the area makes the application credible.
- The debt-to-income ratio. The HCSF standard caps it at 35% of net income before tax, insurance included. The rent counted, after a discount, is added to your income: a well-located house share therefore helps get through.
- Term and deferral. 25 years at most. A deferral of up to 2 years can be added if the works amount to at least 10% of the total cost of the project. During the works, it avoids paying a full monthly instalment without rent: Steve obtained 24 months, Frédéric and Patricia 12 months, Fleur and François 6 months.
- The total cost. Price, notary fees, works and furniture. Several of our members had the works and furniture included in the loan.
To estimate how much you can borrow, use our borrowing capacity calculator for non-residents, which takes your country and part of the rent into account.
The figures of eight of our members’ house shares
Figures taken from our members’ project pages, as they gave them. Rents are monthly, excluding charges.
| Member | Lives in | City | Bedrooms | Rent per month | Loan | Result |
|---|
| Adelaide | United Kingdom | Nantes | 4 | €2,540 | €260,000 over 25 years at 3.4% | 10% gross |
| Alice | Thailand | Angers | 3 | €1,605 | €173,000 at 3.35% | 8.5% gross |
| Lou | Canada | Rodez | 3 | €1,240 | €131,693 at 3.7% | 10% gross |
| Amine | Dubai | Thionville | 3 | €1,700 | Over 25 years | 12.6% gross |
| Fleur and François | Luxembourg | Thionville | 4 | €600 per room | €270,000 at 3.2% | 11% gross |
| Paul | Singapore | Rennes | 5-room flat | €1,900 | €233,000 at 3.66% | Self-financing |
| Steve | Spain | Perpignan | 4 | At least €1,600 | About €140,000 at 3.47% | €500 target cash flow |
| Frédéric and Patricia | Switzerland | Toulouse | 3 | €1,700 to €1,800 | €262,000 over 25 years at 3.48% | Almost self-financing |
Two lessons. Mid-sized towns give very good yields on a small budget: 11% and 12.6% in Thionville, 10% in Rodez. And projects with major works, like Frédéric and Patricia’s in Toulouse, yield less in percentage terms but can create value in the property.
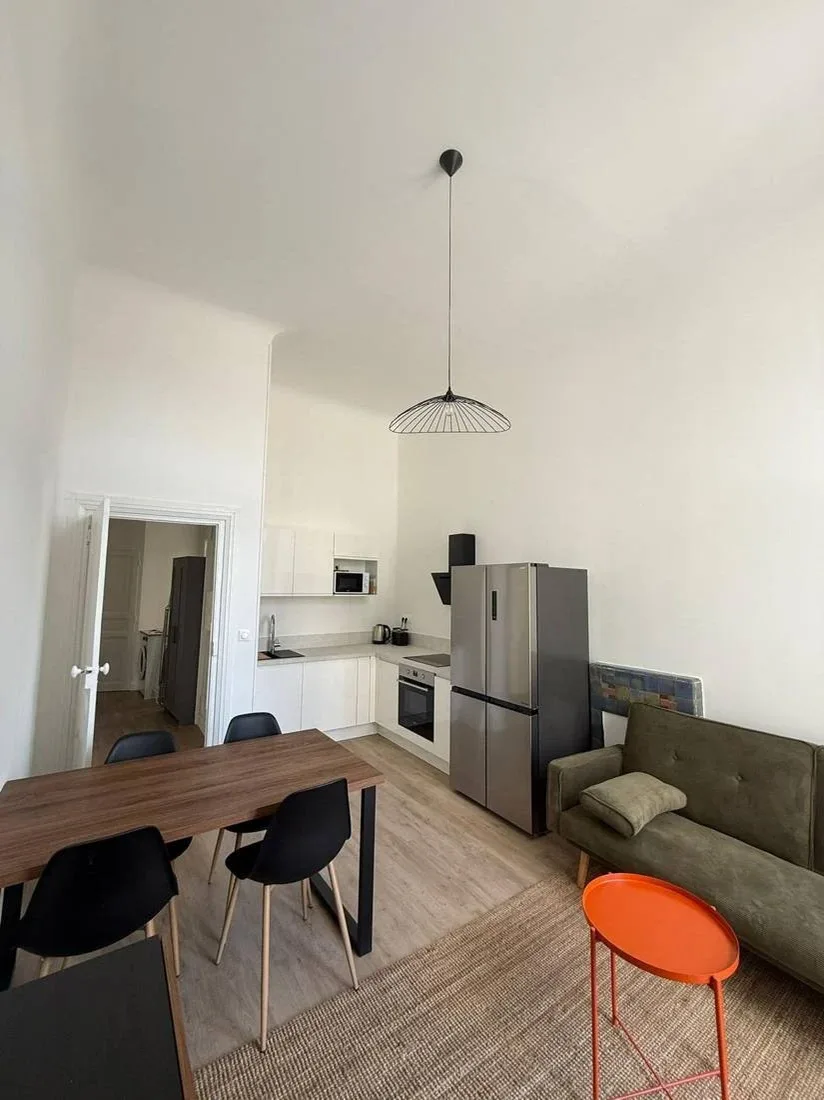
Most of our members buy a family flat and reconfigure it: Thibaud turned the old kitchen into a bedroom in Thionville, Steve is turning a 4-room flat into four bedrooms in Perpignan, Paul made a 5-room flat out of a 4-room one in Rennes. Fleur and François went further, converting commercial premises into a four-bedroom house share.
Three points to check before buying. First, that the property meets the decent-housing rules, energy rating (DPE) included. With one lease per bedroom, each bedroom must be at least 9 m² and 20 m³, and some town halls require a division authorisation or a rental permit. Next, that the co-ownership authorises any works on common parts. Finally, that commercial premises can change use to become housing: prior declaration or building permit depending on the works, and co-ownership rules that allow it.
Letting furnished, room by room
A house share is most often let furnished. Two formulas exist: a single lease signed by all the housemates, often with a joint liability clause, or one lease per bedroom, simpler when a housemate leaves. When furnished, the rent is taxed in France even if you live abroad, as industrial and commercial profits (BIC), usually under the non-professional furnished landlord status (LMNP): our article on LMNP taxation for non-residents details the calculation.
From abroad, a local property manager handles viewings, move-ins and move-outs. It is a cost to plan for in the cash flow calculation, as is a short vacancy between two housemates.
Our team finds properties suited to a house share, estimates the rent per bedroom, has the works priced by our tradesmen, then presents a complete application to our partner banks, the ones that finance non-residents. We then follow the works, the furnishing and the letting. Discover the house share strategy.
Frequently asked questions
Do banks finance house shares for non-residents?
Yes, but not all of them. Those that finance non-residents accept a house share as a rental investment, counting part of the expected rent. Our members were financed from the United Kingdom, Canada, Dubai, Switzerland, Luxembourg, Singapore or Spain.
Can works and furniture be included in the loan?
Yes, it is common. The loan then covers the price, notary fees, works and furniture, often with a deferral during the works. You need tradesmen’s quotes to show the bank.
What yield can you expect from a house share?
Among our members, house shares show gross yields from 8.5% to 12.6%, with the best results in Thionville and Rodez, two mid-sized towns. The yield mainly depends on the purchase price and the rent per bedroom in the area.
Should you use a single lease or one lease per bedroom?
Both are used. A single lease with a joint liability clause lets the owner claim the full rent from each housemate; after a departure, this liability lasts until a replacement joins the lease, and six months at most. One lease per bedroom simplifies departures, but each tenant only owes their own rent, and each bedroom must be at least 9 m² and 20 m³. The choice is made with the property manager depending on the type of tenants.